

Every October, a small group in Stockholm announces who has won the Nobel Prize in Economics. Most people only notice the headline, so the ideas behind the prize rarely get explained.
This guide goes through every year from 1969 to 2026. For each year you get the Nobel Prize in Economics winners, what they worked on, and a short plain-English explanation. I wrote it so that someone with no economics degree can follow it.
A Quick Note Before We Start
The official name is the Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel. Alfred Nobel did not create it in his will. Sweden’s central bank set it up in 1968, and the first prize was given in 1969. It is awarded alongside the original Nobel Prizes and presented on 10 December.
Through 2025 it had been awarded 57 times to 99 people. With the 2026 prize, that makes “58 prizes and 101 laureates”. Only three women have won so far: Elinor Ostrom, Esther Duflo and Claudia Goldin.
The 1970s: Building the Foundations
1969: Ragnar Frisch and Jan Tinbergen
The first prize went to a Norwegian and a Dutchman. They built mathematical models to study how economies move over time. Their work is the starting point of “econometrics”, the use of statistics to test economic ideas.
1970: Paul Samuelson
Samuelson took the language of mathematics and made it standard in economics. His textbook taught generations of students. He also raised the scientific level of the whole field.
1971: Simon Kuznets
Kuznets measured national income and growth using real data. He showed how countries grow, and how “inequality changes as they get richer”.
1972: John Hicks and Kenneth Arrow
Both worked on “general equilibrium” (how all markets in an economy fit together) and welfare economics. Arrow’s famous result shows how hard it is to turn everyone’s preferences into one fair group choice.
1973: Wassily Leontief
He created the “input-output table”. It shows how one industry’s output becomes another industry’s input, such as steel going into cars. Governments still use it for planning.
1974: Gunnar Myrdal and Friedrich Hayek
They disagreed on a lot, yet they shared a prize. Both studied how money, institutions and society affect the economy. Hayek also argued that “no central planner can hold all the knowledge” that scattered markets use.
1975: Leonid Kantorovich and Tjalling Koopmans
They worked independently on the “optimal use of scarce resources”. Their methods became linear programming. Today it helps airlines, factories and delivery firms save money.
1976: Milton Friedman
Friedman studied consumption, the history of money, and why stabilising an economy is harder than it looks. His name is tied to the idea that “inflation is, in the long run, a money problem”.
1977: Bertil Ohlin and James Meade
They explained why countries trade, and how money and capital move across borders. Ohlin focused on differences in resources between countries. Meade focused on policy.
1978: Herbert Simon
Simon argued that people do not make perfect decisions. We have limited time and information, so we settle for “good enough”. He called this “bounded rationality”, and it is a seed of behavioural economics.
1979: Theodore Schultz and Arthur Lewis
Both studied “poor countries”. Schultz showed that education and health are investments, not just spending. Lewis explained how workers shift from farms to industry during development.
The 1980s: Markets, Money and Methods
1980: Lawrence Klein
Klein built large computer-based models of the economy. They were among the first used to forecast and test government policies.
1981: James Tobin
Tobin showed how financial markets connect to spending, jobs and prices. He also suggested a small tax on currency trading, now known as the “Tobin tax”.
1982: George Stigler
Stigler studied how industries are organised and what regulation really does. He found that “regulators often end up serving the industry” they are meant to watch.
1983: Gérard Debreu
Debreu gave general equilibrium theory a strict mathematical proof. He showed when a set of competitive markets can settle at balanced prices.
1984: Richard Stone
Stone designed the system of “national accounts”. When you hear “GDP”, you are hearing the result of his work.
1985: Franco Modigliani
He explained how people save across their lives, saving while working and spending in retirement. This is the “life-cycle hypothesis”. He also did important work on how companies are financed.
1986: James Buchanan
Buchanan applied economics to politics. His “public choice theory” says politicians and officials also follow their own interests, just like everyone else.
1987: Robert Solow
Solow built the basic model of “economic growth”. It showed that technology, not just more machines and workers, drives long-term progress. In its classic form:
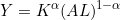
Here  is output,
 is capital,
 is labour and
 is technology.
1988: Maurice Allais
Allais worked on how markets use resources efficiently and how prices should be set in monopolies. He is also known for the Allais paradox, which shows that “people’s choices under risk are not always logical”.
1989: Trygve Haavelmo
He laid the “probability foundations of econometrics”. Haavelmo argued that economic data should be treated as random, so statistical tools work properly.
The 1990s: Finance, Games and Information
1990: Harry Markowitz, Merton Miller and William Sharpe
These three built modern finance. Markowitz showed how to balance risk and return in a portfolio. Sharpe gave us the CAPM formula:
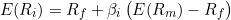
The expected return of an asset equals the risk-free rate plus a reward for the risk it carries. Miller studied how companies choose between debt and equity.
1991: Ronald Coase
Coase asked why companies exist at all. His answer was “transaction costs”, the cost of using the market. He also showed that clear property rights help people settle problems like pollution.
1992: Gary Becker
Becker used economic thinking on topics like crime, family, education and discrimination. Many people thought these were outside economics until he proved otherwise.
1993: Robert Fogel and Douglass North
They brought data and theory into “economic history”. Fogel studied railroads and slavery in America. North showed how rules and institutions shape long-term growth.
1994: John Harsanyi, John Nash and Reinhard Selten
They shared the prize for “game theory”. Nash’s idea is the best known. A Nash equilibrium is a situation where no player gains by changing strategy alone:
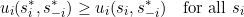
1995: Robert Lucas
Lucas introduced “rational expectations” into macroeconomics. People look ahead, so a policy can change how they behave. Old data may then stop predicting the future.
1996: James Mirrlees and William Vickrey
They studied what happens when one side knows more than the other. Their work on “incentives” helped design better tax systems and auctions.
1997: Robert Merton and Myron Scholes
They found a way to price “options”, a type of financial contract. The Black–Scholes formula (Fischer Black had died by then, so he could not share the prize) is:
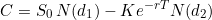
1998: Amartya Sen
Sen worked on welfare, poverty and famine. He showed that “famines often come from lack of access to food” and not just a shortage of it. He also helped create the Human Development Index.
1999: Robert Mundell
Mundell studied how money and government spending work under different exchange rate systems. His work on “optimum currency areas” helped shape the thinking behind the euro.
The 2000s: Evidence, Information and Behaviour
2000: James Heckman and Daniel McFadden
They created tools to study people’s real choices. Heckman dealt with “selection bias” in data. McFadden modelled how people pick between options, such as which transport to use.
2001: George Akerlof, Michael Spence and Joseph Stiglitz
They explained markets where one side knows more than the other. Akerlof’s “market for lemons” shows why used-car buyers fear bad cars. Spence showed how signals like education help. Stiglitz studied insurance and credit markets.
2002: Daniel Kahneman and Vernon Smith
Kahneman showed that people often use mental shortcuts and make “predictable errors”. Smith pioneered laboratory experiments for testing how markets work.
2003: Robert Engle and Clive Granger
Engle built a way to measure changing volatility in financial data, called ARCH:
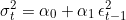
Granger developed “cointegration”, which handles data that drifts together over time.
2004: Finn Kydland and Edward Prescott
They showed why governments struggle to keep promises on policy, known as “time inconsistency”. They also argued that technology shocks help explain business cycles.
2005: Robert Aumann and Thomas Schelling
Both used game theory to understand conflict and cooperation. Schelling’s work on strategy and threats was especially influential in thinking about nuclear deterrence.
2006: Edmund Phelps
Phelps studied the trade-off between inflation and unemployment over time. He also showed how “people’s expectations affect that relationship”.
2007: Leonid Hurwicz, Eric Maskin and Roger Myerson
They created “mechanism design”. It asks how to build rules, like auctions or voting systems, so that people’s own interests lead to a good result.
2008: Paul Krugman
Krugman explained why countries trade similar goods with each other, and why industries cluster in certain places. His work shows the role of “large-scale production”.
2009: Elinor Ostrom and Oliver Williamson
Ostrom, the first woman to win, showed that communities can manage shared resources like fisheries and forests “without government or privatisation”. Williamson studied how firms are organised and why some activities stay inside a company.
The 2010s: Jobs, Prices and Poverty
2010: Peter Diamond, Dale Mortensen and Christopher Pissarides
They studied “search frictions”. Jobs and workers exist at the same time, yet matching takes time. Their model explains why unemployment and job vacancies can both be high.
2011: Thomas Sargent and Christopher Sims
They developed methods to separate “cause from effect” in the economy. For example, they help show how a change in interest rates really affects growth and prices.
2012: Alvin Roth and Lloyd Shapley
Shapley developed theory on stable matching. Roth used it in the real world, such as pairing kidney donors with patients and students with schools. This is “market design”.
2013: Eugene Fama, Lars Peter Hansen and Robert Shiller
They looked at asset prices from different angles. Fama argued markets are hard to beat. Shiller showed prices can move beyond what fundamentals justify. Hansen built statistical methods to test such ideas.
2014: Jean Tirole
Tirole studied big firms with market power and how to regulate them sensibly. His work covers industries like telecoms and banking.
2015: Angus Deaton
Deaton analysed consumption, poverty and well-being using household surveys. His work shows “how to measure living standards properly”.
2016: Oliver Hart and Bengt Holmström
They developed “contract theory”. It explains how to write agreements when you cannot watch everything, such as paying a manager or setting incentives for a CEO.
2017: Richard Thaler
Thaler built “behavioural economics” into the mainstream. His “nudge” idea shows that small changes, such as default options in a pension plan, can change decisions a lot.
2018: William Nordhaus and Paul Romer
Nordhaus put climate change into economic models, which helped create the idea of a carbon price. Romer showed that ideas and knowledge drive long-run growth from within the economy, called “endogenous growth”.
2019: Abhijit Banerjee, Esther Duflo and Michael Kremer
They used “field experiments”, similar to medical trials, to test ways of fighting poverty. Does a free school meal or a bed net help? Now we have real answers.
The 2020s: Recent Winners
2020: Paul Milgrom and Robert Wilson (announced 12 October)
They improved “auction theory” and designed new auction formats. These have been used to sell radio frequencies for mobile phones.
2021: David Card, Joshua Angrist and Guido Imbens (announced 11 October)
Card used “natural experiments” to study the labour market, including the effect of minimum wages. Angrist and Imbens developed the statistical method that lets researchers draw cause-and-effect conclusions from such events.
2022: Ben Bernanke, Douglas Diamond and Philip Dybvig (announced 10 October)
They studied “banks and financial crises”. Diamond and Dybvig explained why bank runs happen. Bernanke showed how the banking collapse made the Great Depression much worse.
2023: Claudia Goldin (announced 9 October)
Goldin traced women’s work and pay across 200 years. She showed “why the gender gap persists” even as education levels rise.
2024: Daron Acemoglu, Simon Johnson and James Robinson (announced 14 October)
They showed that a country’s “institutions”, meaning its rules and who has power, strongly affect whether it becomes rich or stays poor.
2025: Joel Mokyr, Philippe Aghion and Peter Howitt (announced 13 October)
Mokyr studied why sustained growth began with the Industrial Revolution, pointing to useful knowledge and openness to change. Aghion and Howitt built a model of “creative destruction”, where new products replace old ones.
2026: Robert E. Hall and Michael Woodford (announced 12 October)
The newest winners are two American economists. The prize recognised their work on the “microeconomic foundations of macroeconomic stabilisation”. In simple terms, they built the models that help central banks and governments smooth out booms and busts.
The Nobel committee’s chair said their work gives central banks and governments a stable theoretical base for the models they now use. A central idea is that households and businesses look ahead when they decide how much to save or what to charge. This means “what central banks say about the future can matter as much as what they do today”.
Hall is known for work on consumption, unemployment and fiscal policy. Woodford is known for his book Interest and Prices and for ideas like forward guidance. Central banks often think about interest rates using simple rules like this one:
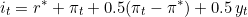
Here  is the policy interest rate,
 is inflation and
 is the output gap. The two winners share the prize money of 12 million Swedish kronor, which is 6 million each.
What the Timeline Tells Us
A few patterns stand out when you read all 58 prizes together:
- Early prizes went to big theory and measurement, such as growth, national accounts and equilibrium.
- The 1990s and 2000s brought game theory, information problems and finance.
- Recent prizes lean toward evidence: experiments, natural experiments and real-world design.
- Behaviour matters. Since 2002, several prizes have shown that “people are not perfectly rational calculators”.
Final Thoughts
The Nobel Prize in Economics is not perfect, and critics point out that it favours certain schools and countries. Still, reading the list from 1969 to 2026 gives you a quick history of how economic thinking has changed. Bookmark this page, because it will be updated when next year’s winners are announced.

 MinhajMetricsHub