

Why Stationarity Matters
A time series  is (weakly, or covariance) stationary if its statistical properties do not change over time. Formally, three conditions hold for every
 :
 — constant mean
 — constant variance
 — depends only on the lag
 , never on

 — constant mean
 — constant variance
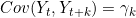 — depends only on the lag
 , never on
These conditions matter because time-series inference is only valid when these properties hold. Regressing one non-stationary series on another produces a high  and significant -statistics even though no real relationship exists between them:
If a series produces a high but a low Durbin-Watson statistic (i.e., positive autocorrelation), this is the case of the spurious or nonsense regression problem (Granger and Newbold, 1974). Therefore, it is necessary to check the stationarity of the time series and correct it before a time-series regression is estimated
Two broad approaches are used to check whether a series is stationary: an informal graphical method and a set of formal unit root tests. This article works through both.
Graphical Method: The Line Plot
Definition
The first and simplest check is to plot the series against time and inspect it visually. A time-series (line) plot places on the vertical axis against on the horizontal axis, in the order the observations occurred.
Procedure
There is no formula to derive here; the check is visual, not statistical. Three features are examined:
- Level — Does the series drift upward or downward over the sample, or does it hover around one constant value?
- Spread — Does the size of the fluctuations around the average grow or shrink over time, or stay roughly constant?
- Shocks — Does the series return to its earlier level after a disturbance, or does the disturbance shift it permanently?
Decision rule
Because this is a visual check, there is no statistical criterion. But generally we can conclude:
- Non-stationary — a trending mean, a widening/narrowing band of fluctuation, or a level permanently shifted by past shocks.
- Stationary — a roughly constant mean and spread, with the series pulled back toward that mean after a shock.
Interpretation
A plot is only ever suggestive — two series can look similar to the eye while only one has a unit root, especially in short samples. The graphical method is used to form a first impression and to decide, for instance, whether to test a series in levels, in first differences, or with a trend included. The formal decision is left to a unit root test.
Unit Root Tests: The Common Framework
DF, ADF, and PP all start from the same idea. Consider a first-order autoregressive process:
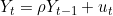
- If
 , the process is a random walk,
 : every shock
 is carried forward permanently, the variance of
 grows with , and the series has a unit root.
- If
 , past shocks decay and the series reverts to a constant mean — it is stationary.
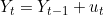 : every shock
 , past shocks decay and the series reverts to a constant mean — it is stationary.
Subtracting  from both sides gives the form actually estimated:
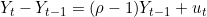
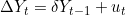 , where

Testing  is therefore identical to testing
 , which is why the tests below are written in terms of
 . The regression may include a constant (drift) and/or a linear trend, giving three commonly estimated forms:
- No constant, no trend:

- With constant:

- With constant and trend:

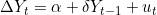
Common hypotheses
H₀: (equivalently ) — the series has a unit root; it is non-stationary
H₁:  (equivalently
 ) — the series has no unit root; it is stationary
This is a one-sided (left-tailed) test:  implies an explosive series, a case rarely entertained in economic data, so the alternative is rather than
 .
Why not use ordinary -critical values?
Under  , is itself non-stationary, so the usual normal-based asymptotic theory behind the -distribution breaks down.
Dickey and Fuller (1979) derived the correct, non-standard limiting distribution and tabulated critical values for it; MacKinnon (1996) later supplied response-surface formulas so critical values and p-values could be computed for any sample size.
This is why software reports “Dickey-Fuller” or “MacKinnon” critical values and p-values here, rather than ordinary or normal ones.
DF, ADF, and PP differ mainly in how they treat the error term  — not in this basic logic.
Dickey-Fuller (DF) Test
Definition
Derivation
Starting from and reparameterising as shown in Section 3 gives the estimating equation (fitted with or without  ,
 , per the three forms above):
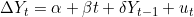
Hypotheses
H₀: — unit root present; is non-stationary
H₁: — no unit root; is stationary
Test statistic

This has the form of an ordinary -ratio, but under it follows the non-standard Dickey-Fuller distribution, not the -distribution. Critical values come from Dickey-Fuller/MacKinnon tables and are more negative than the corresponding /normal critical values at the same significance level.
Decision rule
t-Statistic Method
| Comparison | Decision |
|---|---|
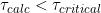 | Reject → Series is stationary |
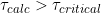 | Fail to reject → Series is non-stationary |
P-Value Method
| p-value method | Decision |
|---|---|
p-value  (e.g. 0.05) | Reject H₀ → series is stationary |
p-value  | Fail to reject H₀ → series is non-stationary |
Interpretation
Rejecting means the series has no unit root at the level tested and can be treated as stationary there. Failing to reject means the series still contains a unit root and should be re-tested after differencing (or with a trend/constant added, as appropriate) until stationarity is achieved.
Limitation
The DF test’s validity rests on being white noise. Economic and financial series are usually autocorrelated, which biases DF toward over-rejecting if left uncorrected — this motivates the ADF test.
Augmented Dickey-Fuller (ADF) Test
Definition
The Augmented Dickey-Fuller (Dickey and Fuller, 1981; Said and Dickey, 1984) test is the modified version of the Dickey-Fuller unit root test used to test the stationarity of a variable. It overcomes the problem of autocorrelation by including the lagged difference of the dependent variable.
Derivation
Starting from the DF equation and adding  lagged difference terms of the dependent variable:
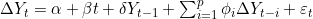
The lag length is chosen so that  is free of serial correlation — commonly by minimising an information criterion (AIC, SBC/BIC, or Hannan-Quinn) across candidate lag lengths.
Another method is to start from a maximum lag, such as Schwert’s rule of thumb, 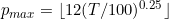 , and drop insignificant higher-order lags.
Hypotheses
H₀: — unit root present; series is non-stationary
H₁: — no unit root; series is stationary
Test statistic
Same form as DF, 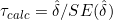 , now computed from the augmented regression. It is compared against the same Dickey-Fuller/MacKinnon critical values, since the two statistics share the same limiting distribution asymptotically.
Decision rule
t-Statistic Method
| t-statistic (τ) method | Decision |
|---|---|
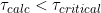 | Reject → Series is stationary |
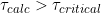 | Fail to reject → Series is non-stationary |
P-Value Method
| p-value method | Decision |
|---|---|
| p-value | Reject H₀ → series is stationary |
| p-value | Fail to reject H₀ → series is non-stationary |
Interpretation
Read exactly as DF, but the conclusion is now robust to the autocorrelation that the lagged-difference terms have absorbed; this is the practical reason ADF is the default choice in applied work.
Phillips-Perron (PP) Test
Definition
The Phillips-Perron test (Phillips and Perron, 1988) tests the same null hypothesis as DF/ADF but, instead of augmenting the regression with lagged differences, corrects the DF test statistic itself for serial correlation and heteroskedasticity in
Derivation
PP starts from the same regression as DF, conventionally written in level form (algebraically equivalent to Section 3’s difference form, with  ):
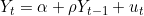

Because may be autocorrelated and heteroskedastic, PP estimates its long-run variance non-parametrically, following Newey and West (1987). With  the OLS residuals,
 the sample size, and
 a truncation lag:
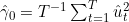
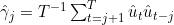
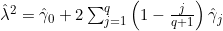
 is the usual short-run residual variance;
 is the long-run variance once serial correlation is accounted for ( is chosen much as ADF’s lag length is, e.g.
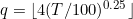 — but only to build this variance estimate, since the regression itself stays unaugmented). The corrected statistic is:
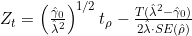
When there is no autocorrelation,  and
 collapses back to the ordinary DF statistic.
Hypotheses
H₀: (equivalently ) — unit root present; series is non-stationary
H₁: (equivalently ) — no unit root; series is stationary
Decision rule
t-Statistic Method
| Comparison | Decision |
|---|---|
 | Reject → Evidence against unit root → Series is stationary |
 | Fail to reject → Evidence of unit root → Series is non-stationary |
P-Value Method
| p-value method | Decision |
|---|---|
| p-value | Reject H₀ → series is stationary |
| p-value | Fail to reject H₀ → series is non-stationary |
is compared against the same Dickey-Fuller/MacKinnon critical values used for DF and ADF, since it shares their asymptotic distribution.
Interpretation
Read exactly as DF/ADF.
Worked Example: Interpreting ADF Results
The two illustrations below are drawn from applied ADF output for macroeconomic series.
p-value method
H₀: series has a unit root (non-stationary)
H₁: series has no unit root (stationary)
Rule: if p-value  , reject H₀ → stationary; if p-value
 , fail to reject H₀ → non-stationary.
| Variable | Level — Intercept | Level — Intercept & Trend | 1st Diff. — Intercept | 1st Diff. — Intercept & Trend | Conclusion |
|---|---|---|---|---|---|
| LCPI (log CPI) | 0.869 | 0.093 | 0.015 | 0.088 | I(1) |
| LM2 (log money supply) | 0.801 | 0.165 | 0.000 | 0.000 | I(1) |
| LY (log GDP) | 0.060 | 0.943 | 0.001 | 0.000 | I(1) |
| LGEXP (log govt. expenditure) | 0.876 | 0.426 | 0.000 | 0.000 | I(1) |
Interpreting LCPI
At level: p-values are 0.869 (intercept) and 0.093 (intercept & trend), both → fail to reject H₀ → LCPI is non-stationary at level.
At first difference: p-values fall to 0.015 and 0.088. The intercept-only p-value (0.015) is below 0.05, so H₀ is rejected at the 5% level; the intercept-and-trend p-value (0.088) clears the 10% threshold rather than 5%. Either way, H₀ is rejected once significance is judged at the level the p-value actually clears.
Conclusion: LCPI is non-stationary in levels but becomes stationary after first differencing — it is integrated of order one, I(1). The same pattern holds for LM2, LY, and LGEXP above, so all four series are I(1).
t-statistic method
Critical value at the 5% level of significance:  .
H₀: series has a unit root (non-stationary)
H₁: series has no unit root (stationary)
Rule: if ADF t-stat  (more negative), reject H₀ → stationary; if ADF t-stat
 , fail to reject H₀ → non-stationary. Equivalently, by p-value: reject H₀ if p-value .
| Variable | t-stat, Level | p-value, Level | t-stat, 1st Diff. | p-value, 1st Diff. | Order of Integration |
|---|---|---|---|---|---|
| Inflation | 0.770 | 0.9917 | −3.624 | 0.0245 | I(1) |
| GDP | −3.743 | 0.0077 | −7.331 | 0.0000 | I(0) |
Interpreting GDP
At level: t-statistic  , critical value at 5%
 . Since
 is more negative than , H₀ is rejected. The p-value confirms this:
 .
Conclusion: GDP is already stationary at level — no differencing is required, so it is integrated of order zero, I(0). Both decision routes (t-statistic and p-value) agree, as they always will since they are two views of the same test.
Interpreting Inflation (contrast case)
At level: t-statistic  — not more negative than — so H₀ is not rejected; the p-value, 0.9917, confirms this decisively. Inflation is non-stationary at level.
At first difference: t-statistic  , more negative than → reject H₀; p-value
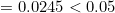 agrees.
Conclusion: Inflation is integrated of order one, I(1) — the more common outcome for macroeconomic series, which is what makes GDP’s stationarity at level (above) the noteworthy exception in this dataset.
Summary Comparison
| Method | Type | How it handles autocorrelation in errors | Needs a lag length choice? | Hypotheses & critical values |
|---|---|---|---|---|
| Line plot | Graphical, informal | Not applicable — visual inspection only | No | No formal test |
| DF | Formal, parametric | Assumes none (white-noise errors) | No | Baseline: Dickey-Fuller / MacKinnon |
| ADF | Formal, parametric | Adds lagged  terms to whiten the errors | Yes () | Same  ; same critical values as DF (asymptotically) |
| PP | Formal, non-parametric | Corrects the DF statistic via a Newey-West long-run variance | Only a truncation lag () for the variance estimate | Same ; same critical values as DF/ADF |
In practice: start with a line plot to form a first impression, then confirm with one or more unit root tests. If ADF and PP disagree, it usually signals that the error structure needs more care.
References
Dickey, D. A., & Fuller, W. A. (1979). Distribution of the Estimators for Autoregressive Time Series with a Unit Root. Journal of the American Statistical Association, 74(366), 427–431.
Dickey, D. A., & Fuller, W. A. (1981). Likelihood Ratio Statistics for Autoregressive Time Series with a Unit Root. Econometrica, 49(4), 1057–1072.
Phillips, P. C. B., & Perron, P. (1988). Testing for a Unit Root in Time Series Regression. Biometrika, 75(2), 335–346.
Newey, W. K., & West, K. D. (1987). A Simple, Positive Semi-Definite, Heteroskedasticity and Autocorrelation Consistent Covariance Matrix. Econometrica, 55(3), 703–708.
MacKinnon, J. G. (1996). Numerical Distribution Functions for Unit Root and Cointegration Tests. Journal of Applied Econometrics, 11(6), 601–618.
Granger, C. W. J., & Newbold, P. (1974). Spurious Regressions in Econometrics. Journal of Econometrics, 2(2), 111–120.

 MinhajMetricsHub